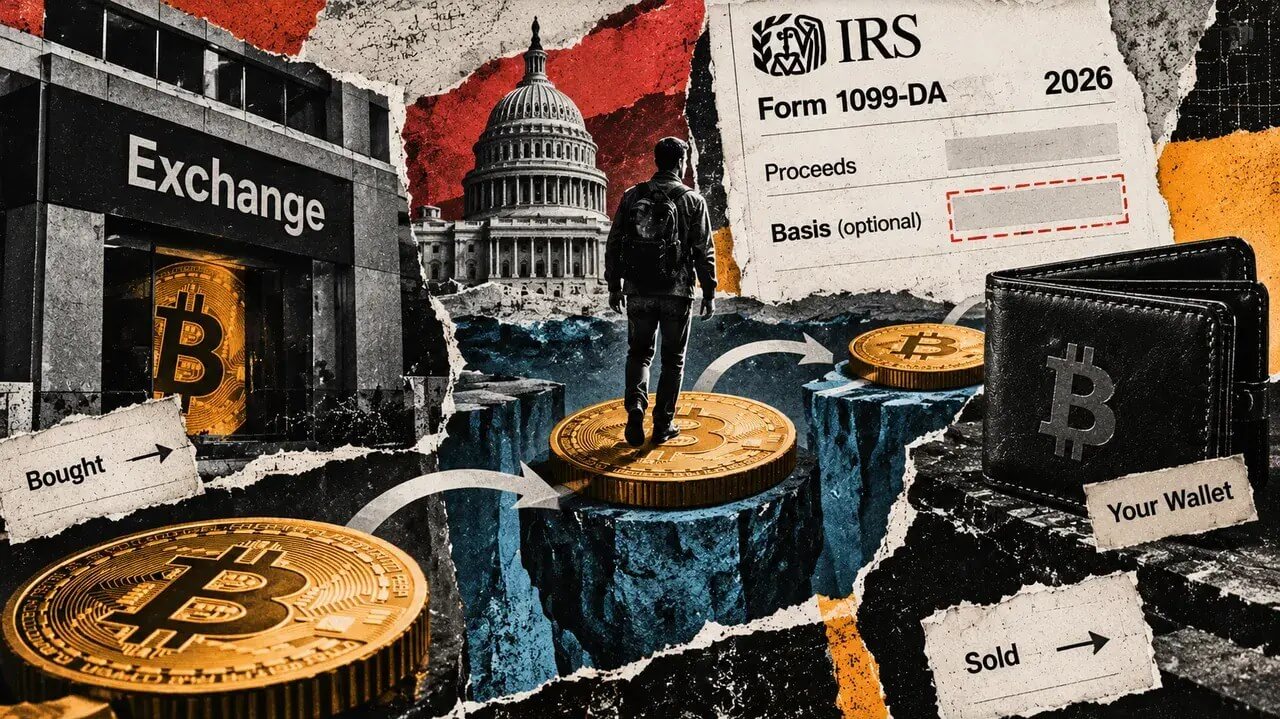
The 2026 US crypto tax rules create a significant 'blind spot' for self-custody users because mandatory broker reporting requirements do not extend to private, unhosted wallets. While centralized exchanges are now required to issue Form 1099-DA documenting transaction details, these forms often lose track of an asset's original purchase price—the cost basis—the moment a user moves their Bitcoin to a hardware wallet or private software. Consequently, the IRS receives notice of the eventual sale but lacks the automated data to verify the initial investment, potentially leading to disputes over tax liabilities.
This regulatory landscape stems from the phased implementation of the Infrastructure Investment and Jobs Act's tax provisions, which aim to increase transparency in the digital asset space. However, the technical nature of decentralized transfers means that 'basis' information does not 'travel' with the coin across the blockchain in a way that satisfies IRS reporting standards for brokers. This effectively bifurcates the market into reported custodial assets and unreported self-custodial assets, complicating the filing process for long-term holders who prioritize security through private storage.
For the crypto market, this implies a higher administrative hurdle for Bitcoin adoption among US taxpayers. Investors who fail to maintain meticulous secondary records of their acquisition costs may find themselves hit with 'zero-basis' assumptions by tax authorities, which maximizes the taxable gain on every sale. This creates a hidden cost to self-custody that could influence how retail investors interact with DeFi and private storage solutions throughout 2026.
Moving forward, investors should watch for the release of final IRS guidance regarding 'transfer statements' between brokers and the potential for new software tools designed to bridge the gap between exchange data and private wallet history. As enforcement ramps up in 2026, the clarity of an investor's internal ledger will be the only defense against the automated reporting gaps inherent in the current US tax framework.