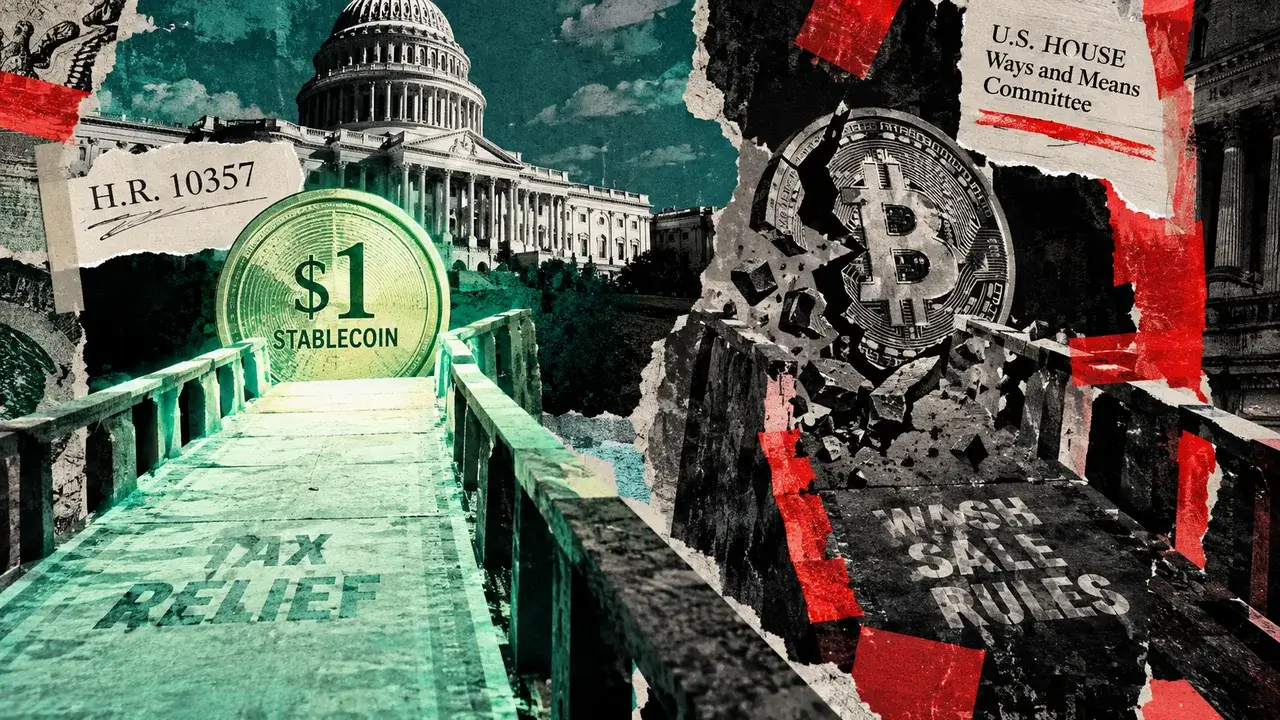
H.R. 10357, a significant legislative development in 2026, reshapes the U.S. crypto tax landscape by reducing the friction associated with everyday digital asset payments, transaction fees, and qualifying crypto-collateralized loans. The bill aims to treat small-scale crypto transactions more like currency by exempting certain minor payments from capital gains triggers, a move that encourages the use of stablecoins and Bitcoin for retail commerce. However, this ease of use comes with a fiscal trade-off: the legislation widens loss-deferral rules and updates trader-accounting standards to generate an estimated $500 million in new tax revenue.
From a political and regulatory standpoint, Congress is attempting to balance mainstream adoption with fiscal responsibility. By easing the tax reporting requirements on qualifying loans, the bill provides much-needed clarity for the decentralized finance (DeFi) sector, where lending and borrowing are core activities. At the same time, the expansion of loss-deferral rules—essentially applying 'wash sale' style restrictions more broadly to digital assets—ensures that professional traders cannot easily offset their gains with artificial losses, a practice the IRS has targeted for years.
Market implications are generally constructive for the utility of major assets like Bitcoin (BTC) and Ethereum (ETH). By removing the 'tax headache' from small transactions and network fees, the bill could significantly increase the velocity of on-chain activity. However, the $500 million revenue target suggests that data sharing between exchanges and the IRS will become more automated and transparent, potentially leading to a period of adjustment for traders who previously relied on ambiguous accounting methods.
Retail investors, DeFi users, and high-frequency traders are the primary groups affected by these changes. As we move through 2026, market participants should watch for specific Treasury Department guidelines regarding the definition of 'qualifying loans' and the exact monetary thresholds for tax-exempt payments. The successful implementation of H.R. 10357 will likely serve as a blueprint for how the U.S. government intends to tax the maturing digital economy without stifling technical innovation.