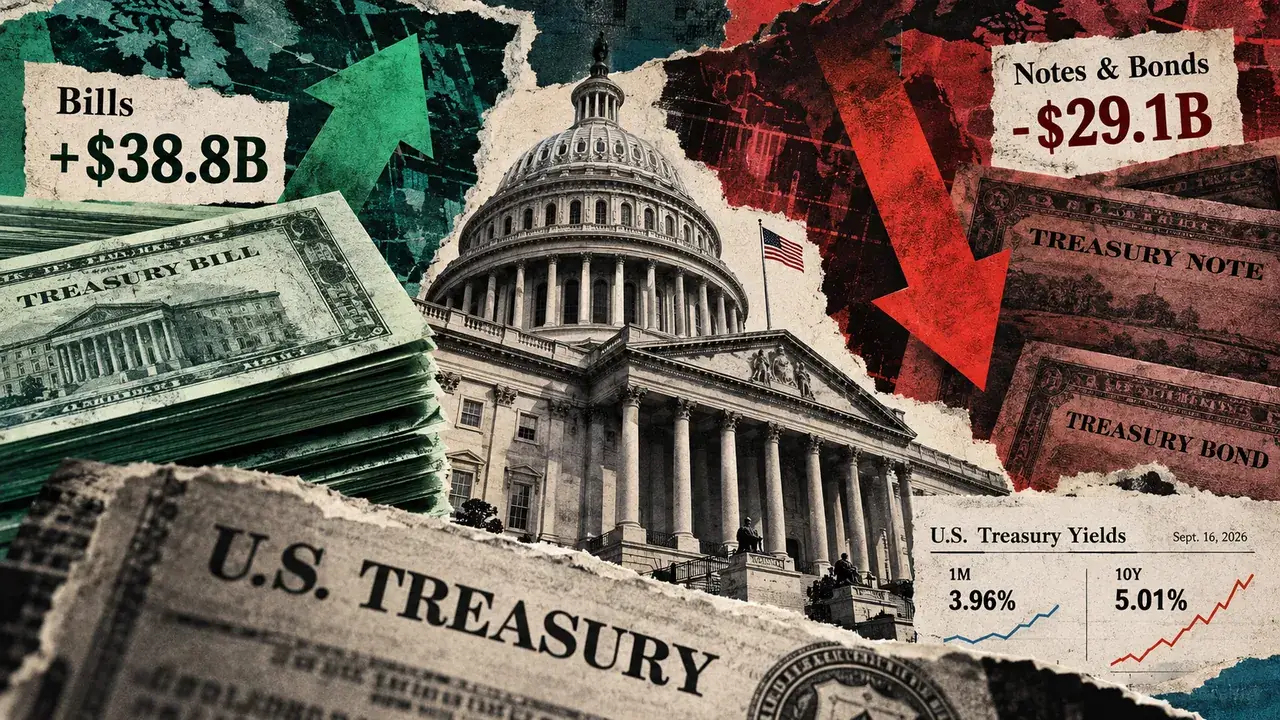
The $29 billion private exodus from long-dated US Treasuries is stalling Bitcoin’s rally because it has forced 10-year yields to remain near the 5% threshold, providing institutional investors with a high-yield, low-risk alternative to digital assets. While official government buying has managed to offset some of the private sector’s selling pressure, the persistent yield levels have increased the 'hurdle rate' for risk-on investments. Consequently, Bitcoin is struggling to attract the necessary liquidity to breach its current resistance levels as capital remains locked in the fixed-income market.
In the third quarter of 2026, the bond market has shown a distinct split between short-term and long-term maturities. While July saw a rebound in Treasury bill demand, the longer-dated 10-year notes are facing a private sector retreat. This divergence suggests that while liquidity is available for short-term needs, private institutions are skeptical of long-term US debt, leading to a massive sell-off that the government is struggling to fully absorb through official channels.
This macroeconomic environment creates a difficult backdrop for the crypto market. When US Treasuries offer a guaranteed 5% return, the risk premium required for Bitcoin becomes significantly higher. For the US-focused crypto investor, this means that the anticipated post-halving rally of 2026 is facing unexpected competition from the traditional finance sector. The 'crowding out' effect of high government yields is effectively siphoning the speculative capital that typically drives Bitcoin’s parabolic moves.
Moving forward, market participants should closely watch the September yield data and any potential intervention from the Federal Reserve. If private selling continues to outpace official buying, yields may climb even higher, placing further downward pressure on BTC. A reversal of this trend—either through a cooling of bond yields or a shift in Fed policy—would likely be the primary catalyst needed to reignite the Bitcoin bull market in late 2026.