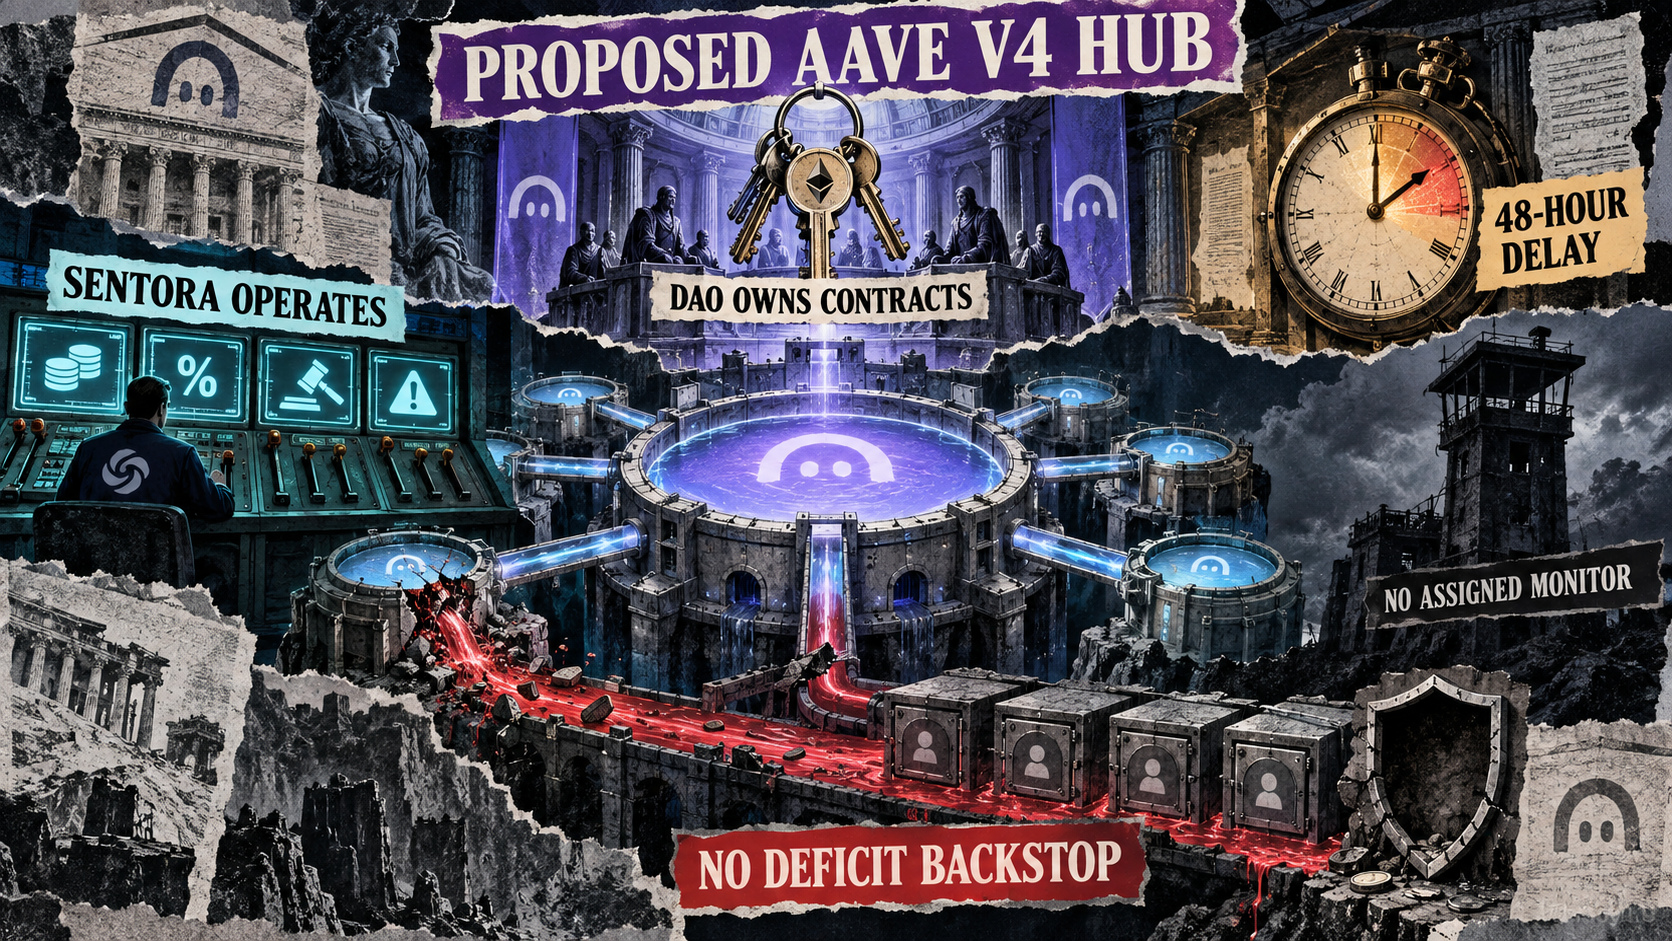
The proposed Sentora integration with Aave creates a lopsided risk profile where Sentora claims 50% of the revenue while suppliers bear the entirety of potential protocol losses. Under this plan, the Aave DAO retains the underlying contracts, but Sentora is granted authority to set market risk controls. Crucially, the current framework lacks a loss cushion, meaning if a market event triggers a deficit, the suppliers—not Sentora—are the ones who face capital impairment.
This development comes at a time in 2026 when DeFi risk management is under intense scrutiny by US regulators, who are increasingly looking at how protocols distribute systemic risks versus rewards. By setting risk parameters without providing financial backing or collateral for those decisions, Sentora is positioning itself as a service provider with high upside and minimal downside exposure. For Aave suppliers, this means their yield is effectively halved to pay for Sentora’s management, while their principal remains fully exposed to the volatility of the markets Sentora controls.
From a market perspective, this could lead to a migration of liquidity away from Sentora-managed Aave markets if suppliers feel the 50% revenue share does not justify the lack of protection. Analysts are watching to see if the Aave DAO will demand a 'first-loss' capital contribution from Sentora to align incentives. If the proposal passes as is, it may set a precedent for 'asset management' layers in DeFi that prioritize protocol fees over supplier safety.
Investors and liquidity providers should closely monitor the upcoming DAO governance votes and any amendments regarding a 'safety module' or loss buffer. The outcome will likely influence how other third-party risk managers integrate with major lending protocols throughout the remainder of 2026. If suppliers reject the lopsided terms, it could force a shift toward more equitable insurance-backed models in the decentralized lending space.