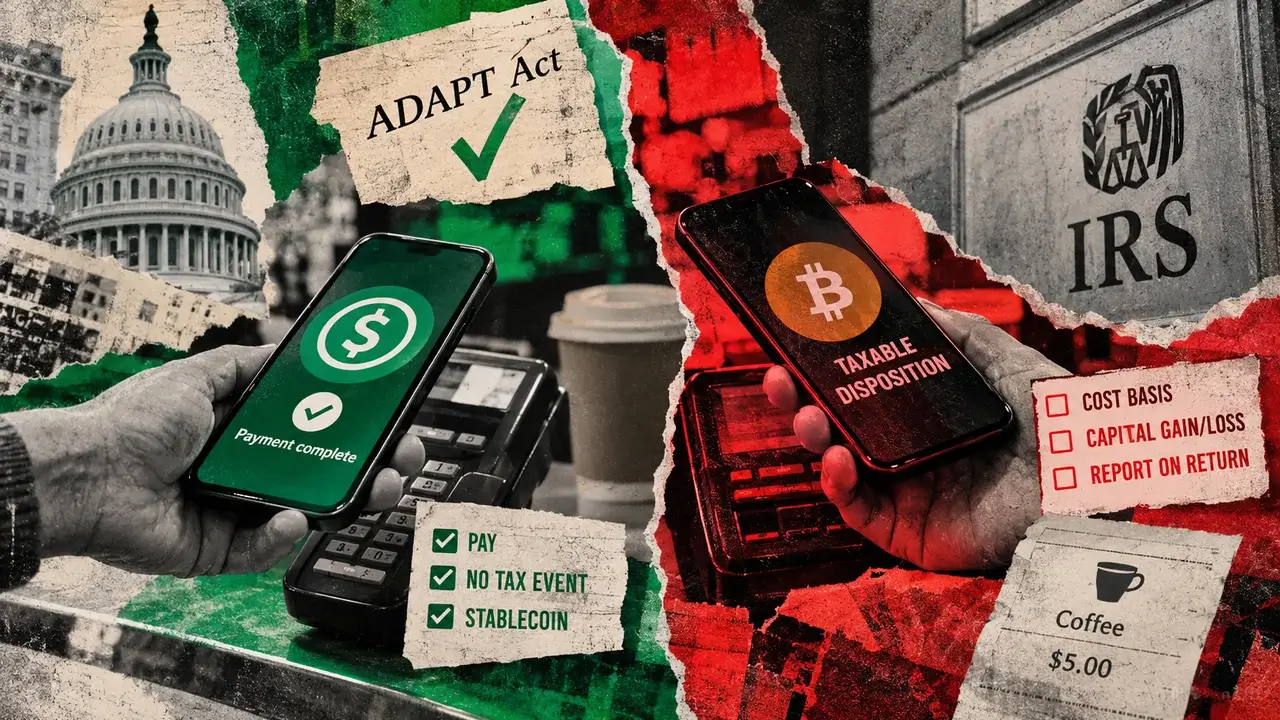
The proposed Senate tax bill creates a significant regulatory divide by exempting dollar-denominated stablecoins from capital gains taxes while maintaining strict reporting requirements for Bitcoin. Under the new rules, eligible stablecoin transactions would receive 'no-gain/no-loss' treatment, meaning users can spend them for goods and services without calculating price fluctuations for tax purposes. Conversely, Bitcoin spending continues to be treated as a disposition of property, requiring taxpayers to report every transaction to the IRS.
This legislative shift is designed to promote stablecoins as a viable medium of exchange within the U.S. economy. By removing the tax friction and the 'value cap' typically associated with de minimis exemptions, the bill allows consumers to use stablecoins for both small and large purchases with the same ease as traditional cash. For Bitcoin holders, the status quo remains a significant barrier to adoption for daily payments, as the IRS still views each satoshi spent as a taxable event based on the asset's fair market value at the time of the trade.
The bill reflects a growing consensus in Washington that stablecoins should be integrated into the payments infrastructure, while Bitcoin should be preserved as a store-of-value asset. Lawmakers argue that providing stablecoins with a tax-free spending status reduces the administrative burden on both the IRS and individual taxpayers, who previously had to track negligible price deviations of pegged assets like USDC or USDT.
For investors and retail users, this development signals a clear path for stablecoin utility in the 2026 fiscal year. If the bill passes, it could lead to a surge in merchant integration for stablecoin payments, as the accounting hurdle is effectively removed. Readers should closely watch the Senate Finance Committee for potential amendments that might introduce a threshold cap or specific eligibility requirements for which stablecoins qualify for this 'no-gain/no-loss' status.