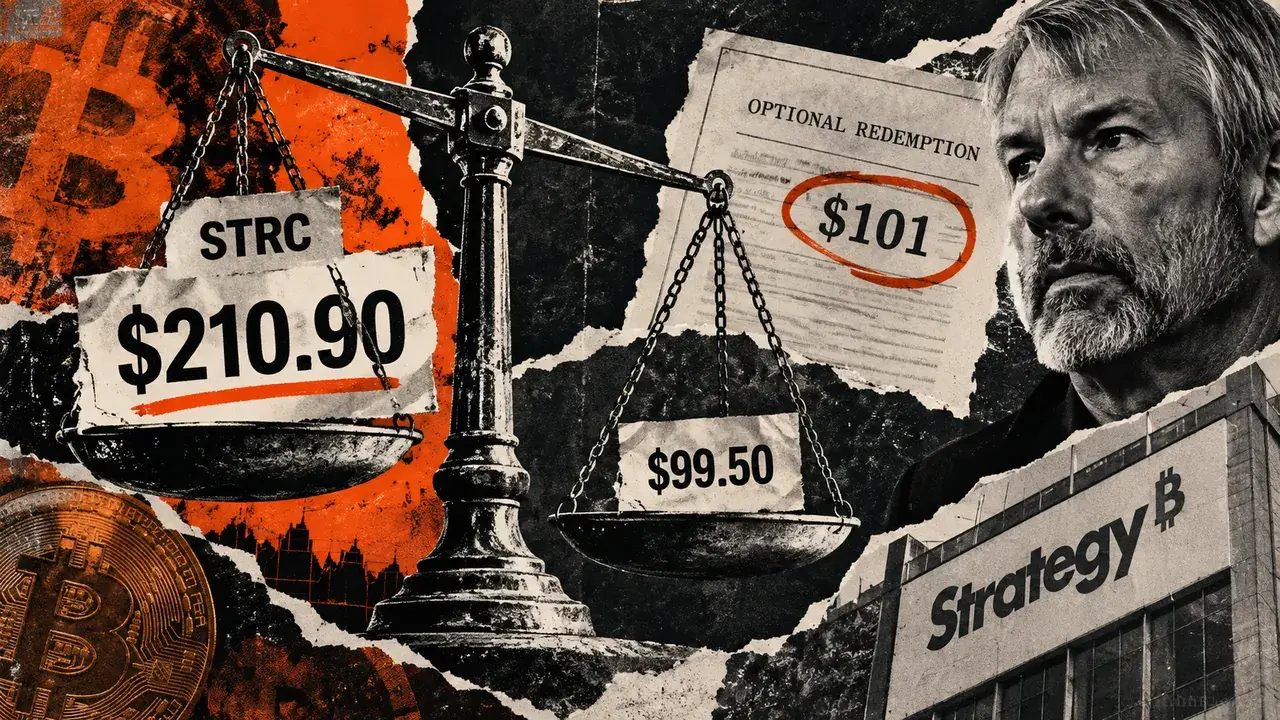
The STRC calculator shows a $210 valuation because it projects the future value of constant dividend payments without accounting for the issuer's right to redeem shares at $101. While the calculator serves as an illustrative tool for potential yield, Strategy maintains the legal option to call these shares at the lower price point plus any accrued dividends. This creates a significant delta that investors must navigate when assessing the actual market value of their holdings.
This technical gap, identified in reports on October 2, 2026, stems from how Strategy calculates long-term holder value versus its immediate financial liabilities. The $210 output assumes that the current dividend environment remains static and that no redemption occurs, providing a "best-case" yield scenario. Conversely, the $101 redemption price is a hard cap defined in the share agreement, allowing the company to limit its payout obligations if the cost of dividends exceeds the cost of buying back the equity.
For US-based crypto investors and hybrid equity holders, this situation highlights the necessity of scrutinizing automated valuation tools in the DeFi and tokenized equity space. The discrepancy is not necessarily a software error but a reflection of two different financial realities: theoretical cash flow versus contractual settlement. Market analysts suggest that reliance on the higher figure without acknowledging the redemption clause could lead to inaccurate risk assessments.
Looking forward, market participants should monitor Strategy’s official redemption announcements closely throughout the remainder of 2026. If the company decides to exercise its $101 redemption option, the higher valuation projected by the calculator will effectively be nullified for current holders. Investors are advised to treat the $101 mark as the realistic exit floor rather than expecting the $210 projection to materialize in a liquidation event.