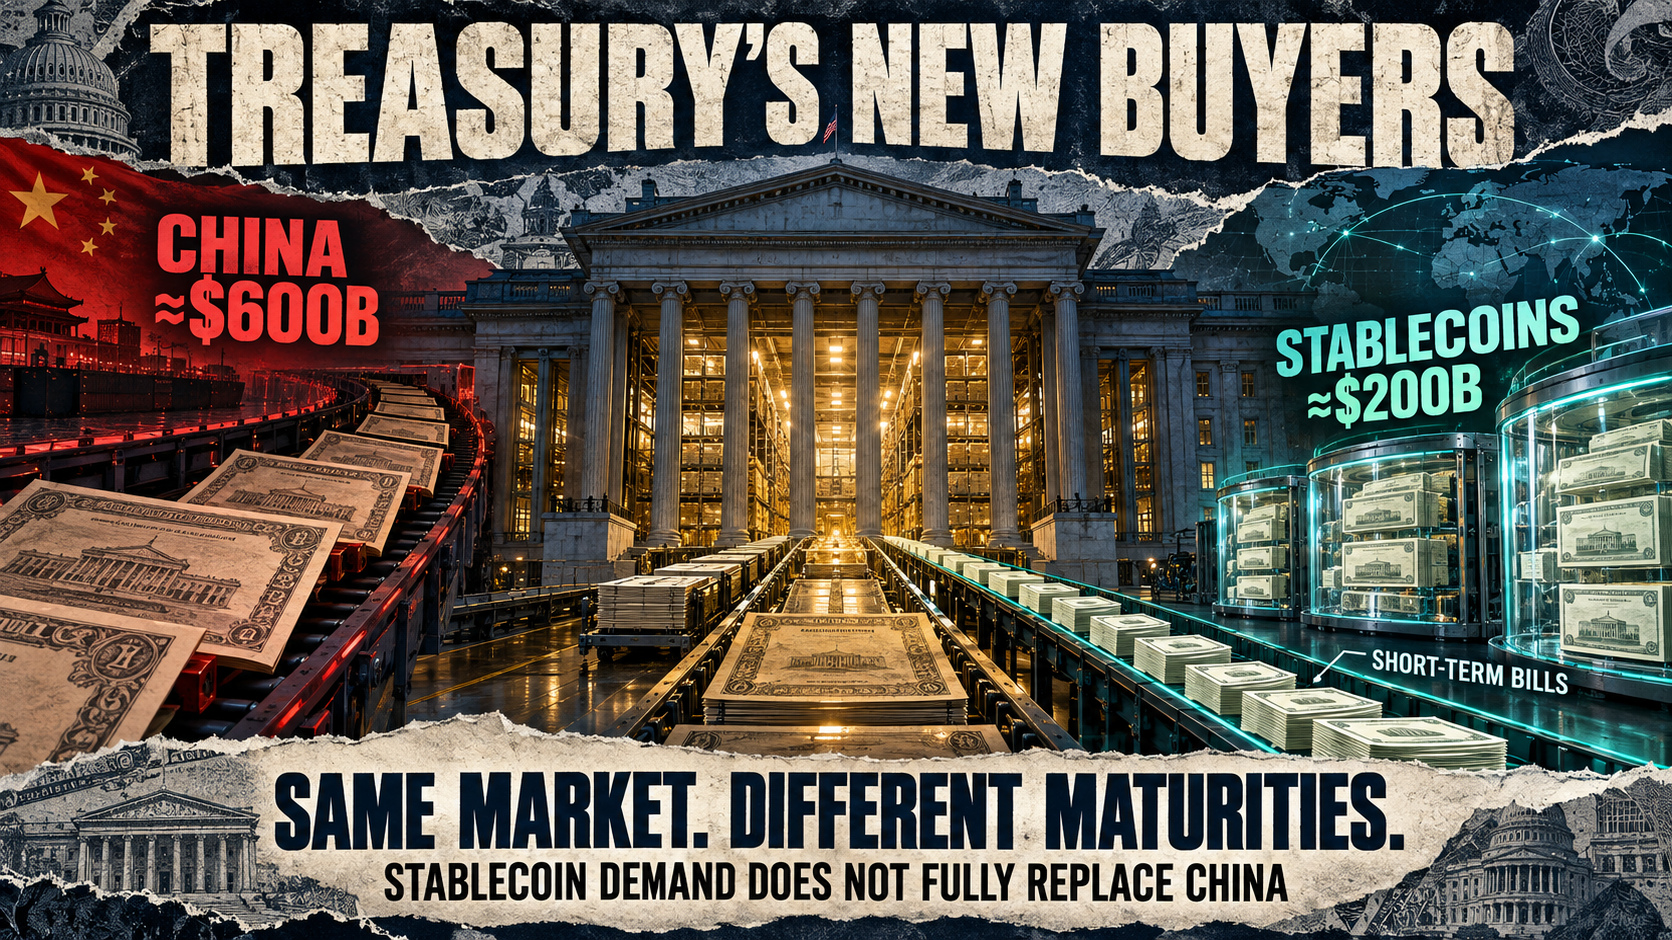
As of early 2026, stablecoin giants Tether and Circle have effectively filled a massive vacuum in the US government debt market, replacing 40% of the demand lost by China’s multi-year divestment. By increasing their combined holdings of US Treasury securities and repurchase agreements by approximately $200 billion since 2021, these issuers have transitioned from niche crypto players to systemic participants in the global financial system. This trend highlights a growing reliance by the US Treasury on digital asset reserves to maintain liquid debt markets.
The shift comes as geopolitical tensions and reserve diversification strategies have led foreign central banks, most notably China's, to scale back their exposure to US debt. In contrast, the rapid expansion of the stablecoin market has necessitated a massive influx of high-quality, dollar-denominated collateral. Tether (USDT) and Circle (USDC) now represent a significant portion of the 'non-bank' demand for Treasuries, effectively tethering the stability of the US dollar's global standing to the health of the crypto ecosystem.
From a regulatory perspective, this development complicates the US government's stance on the industry. While lawmakers remain concerned about consumer protection and illicit finance, the fact that stablecoin issuers are actively supporting the US national debt makes them an essential ally for the Treasury Department. Analysts expect this to accelerate the passage of the 2026 Stablecoin Act, as politicians seek to formalize the rules for these entities to ensure they remain a reliable source of demand for government bonds.
For investors and market participants, this institutionalization provides a layer of security for the underlying assets of the major stablecoins. As Tether and Circle become increasingly integrated into the US financial infrastructure, they become 'too big to fail' in a traditional sense. Moving forward, readers should watch for the Treasury's quarterly refunding announcements, which may now explicitly or implicitly account for stablecoin demand as a primary driver of market liquidity.