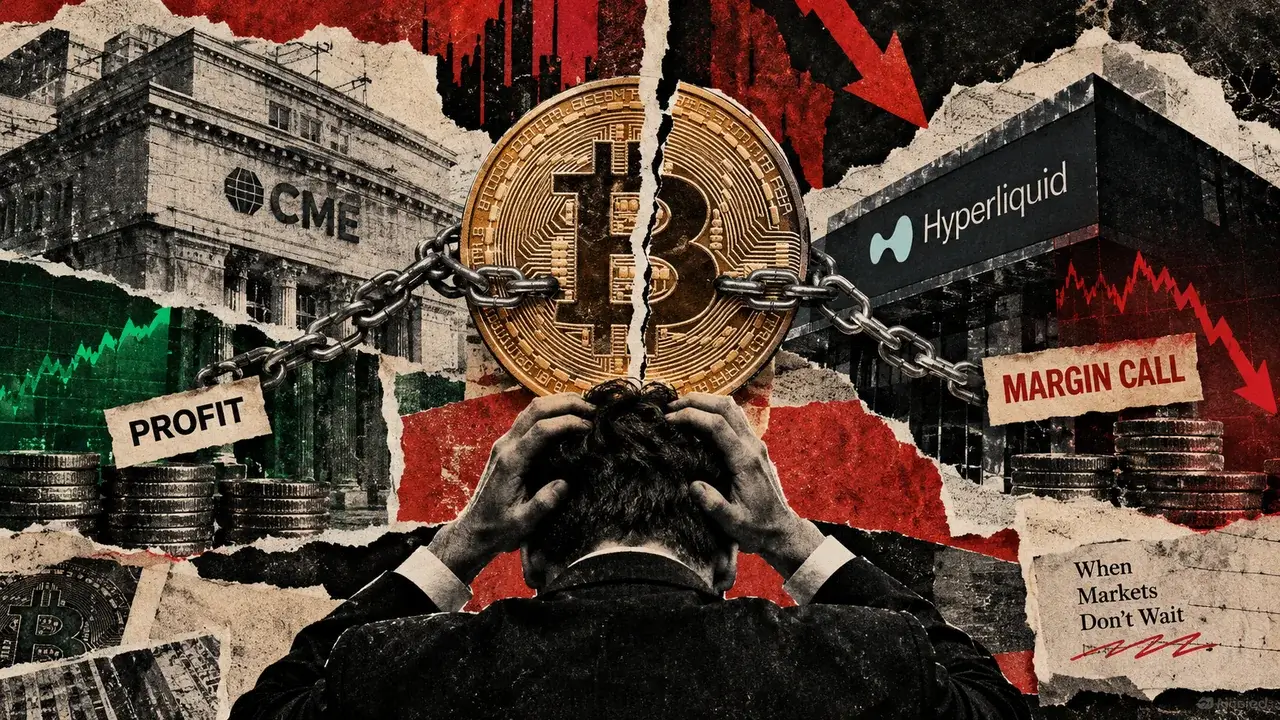
Cross-market collateral fragmentation causes hedge fund liquidations by creating a mismatch between profitable positions and margin-depleted accounts across different trading venues. In a typical 'basis trade,' a fund might hold a short position on the CME and a matching long position on a decentralized exchange like Hyperliquid. If the price of Bitcoin drops, the CME short generates profit, but the Hyperliquid long incurs losses. Because these exchanges operate in silos, the profits from the CME cannot be used to satisfy the margin requirements on Hyperliquid, leading to an automatic liquidation of the long position even if the fund is net-profitable.
This phenomenon has become a critical concern in the 2026 market as institutional capital increasingly flows into decentralized perpetual platforms. The inability to share collateral—or 'cross-margin'—between centralized and decentralized environments means that sudden volatility triggers cascading liquidations. These liquidations are not caused by bad bets, but by the physical time and friction required to move assets between markets to rebalance collateral during high-stress periods.
The implications for the broader Bitcoin market are significant, as these forced liquidations can exacerbate downward price pressure. When a fund’s long leg is liquidated, the exchange must sell the underlying asset, often into a thinning order book, which can drive prices even lower and trigger further margin calls for other participants. This 'liquidity trap' highlights a major structural weakness in the current crypto market architecture that differs from traditional finance, where prime brokers often consolidate margin for their clients.
Looking ahead through the remainder of 2026, investors should watch for the emergence of cross-venue margin protocols and institutional-grade bridge solutions designed to mitigate this risk. Regulatory clarity in the US regarding custodial requirements for hybrid CEX-DEX strategies will also be a key factor in whether funds can successfully navigate these fragmented markets without facing systemic liquidation risks.