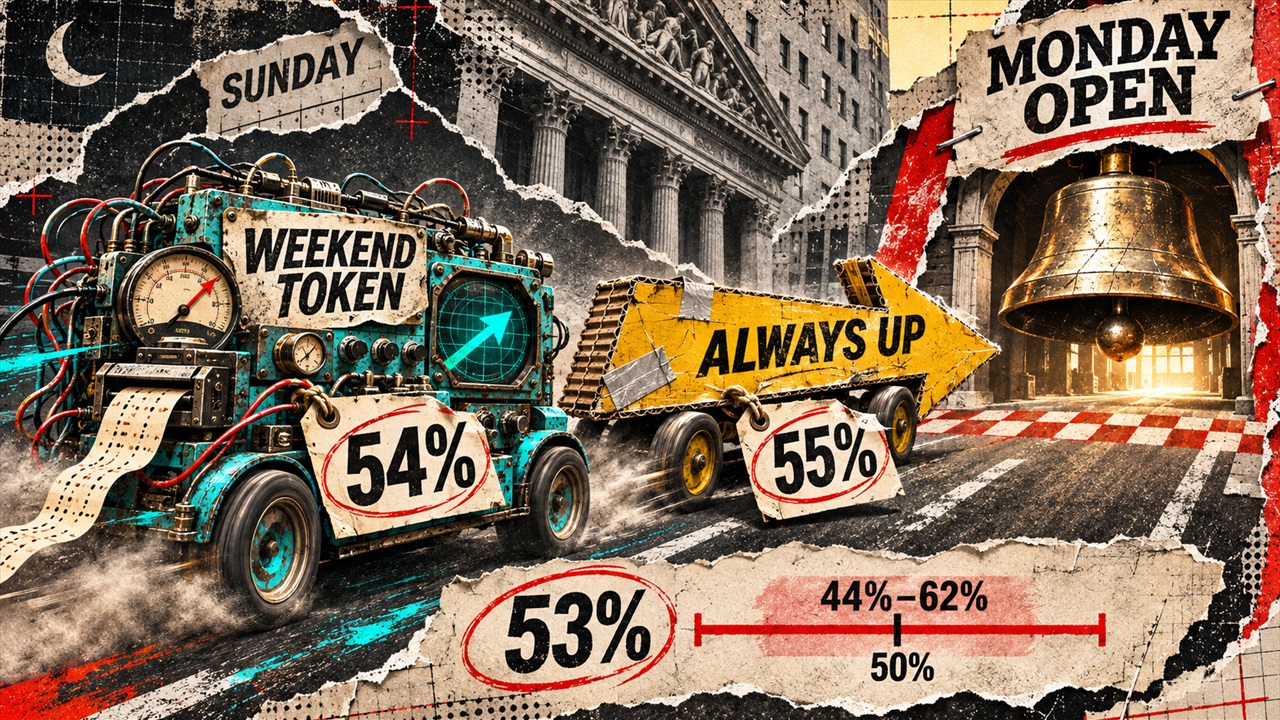
Weekend stock tokens do not provide a reliable directional edge for predicting Monday's US market opening prices, according to a Bitquery pre-futures test conducted in early 2026. The study revealed that guessing a market rise based on weekend token activity scores only a 55% accuracy rate, which is barely better than a coin flip. For traders at WodCrypto looking to front-run traditional market volatility, this suggests that synthetic assets remain more of a sentiment gauge than a precision arbitrage tool.
The research highlights a significant decoupling between the low-volume, retail-driven crypto environment and the high-volume institutional flow that defines the Nasdaq and NYSE opening gaps. Because synthetic tokens trade 24/7, they often react to weekend headlines that traditional markets have yet to price in. However, the lack of institutional participation in these crypto proxies means they often fail to capture the massive 'dark pool' and pre-market orders that actually set the Monday morning price.
This findings come at a time when Nasdaq is exploring a proposed expansion of its weekday trading hours to better compete with the 24/7 nature of digital assets. While the expansion remains conditional on regulatory hurdles and industry consensus, the move signals a growing recognition that traditional finance must adapt to a round-the-clock global economy. If Nasdaq successfully extends its hours, the utility of weekend crypto-based stock tokens may diminish as direct equity trading absorbs that liquidity.
For US-based crypto investors, these results emphasize the need for caution when using synthetic assets to hedge equity positions. The 55% success rate for 'up' moves indicates that while there is a slight correlation, the risk of a 'fake-out' remains high. Traders should watch for the SEC's upcoming decision on exchange hour expansions and monitor whether major crypto platforms like Binance or Coinbase adjust their synthetic offerings to better track institutional pre-market data.